The updated Lada Niva Legend received a new 1.8 engine with a capacity of 90 hp, a timing belt and a number of design changes. But for a potential owner, another question is more important: how much will they have to pay for the car if they do not pay all at once. With a long-term loan, the price of Niva can increase to approximately 2.1 million rubles.
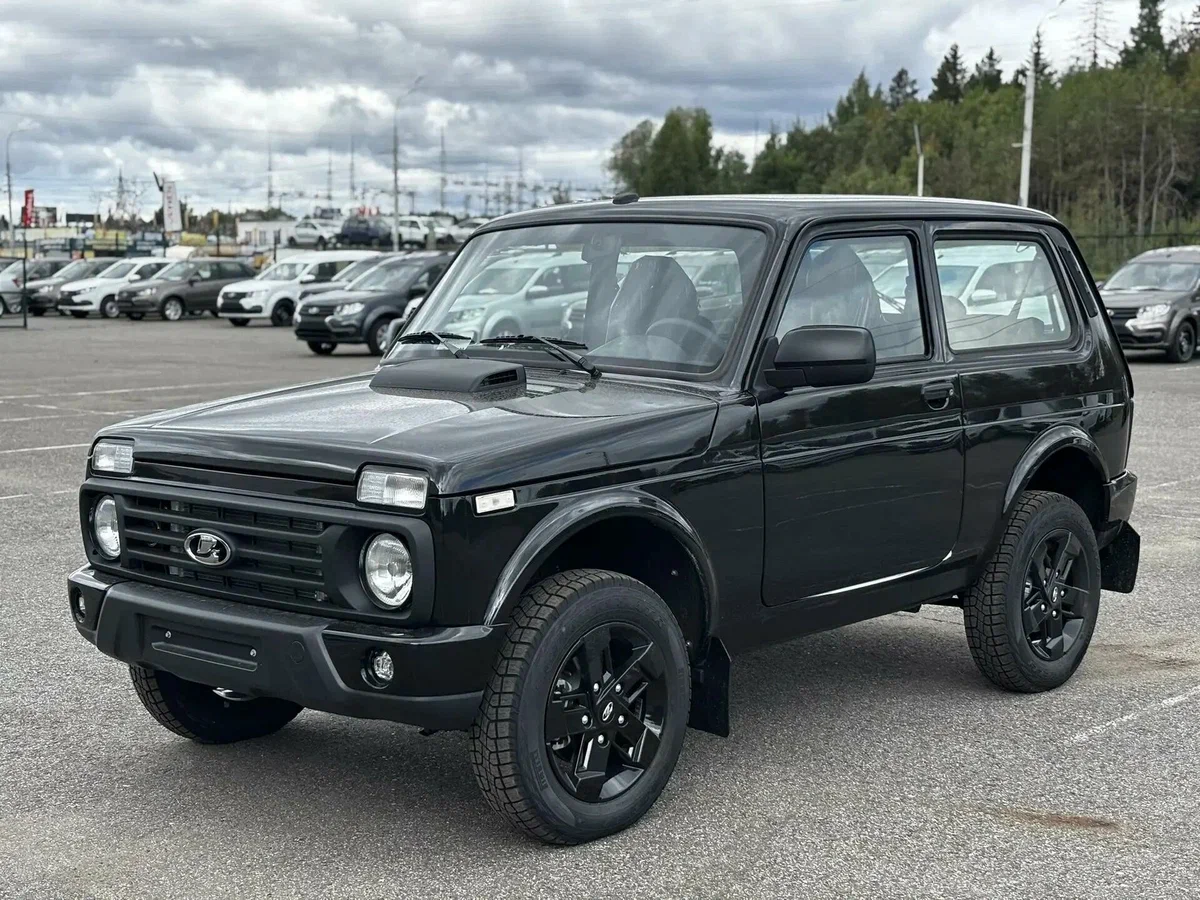
The three-door Niva has a new argument in the fight for buyers – an updated power unit.

The previous 1.7 engine has been retired, and its place has been taken by an eight-valve 1.8 with a capacity of 90 hp. The timing belt design has also changed: a belt is used instead of a chain. Engineers have redesigned the cooling system and transferred some of the attachments.
Changes have also affected safety. A steering column with a driver’s airbag appeared in the cabin.
In the Urban configuration, the three-door looks noticeably more interesting than the basic version: the bumpers are painted in the body color, fog lights and alloy wheels are provided, and the interior received additional brown trim elements.

The price is far from Soviet – 1.35 million rubles .
And if borrowed funds are used to purchase the car, this figure becomes only the starting point.
Down payment – 270 thousand rubles
One of the lending options involves an initial payment of 20%.

With a car price of 1,350,000 The buyer will need to find 270,000 rubles .
A loan is issued for the remaining amount. However, in the program under consideration, it also includes CASCO insurance costing approximately 50,000 rubles.
As a result, the loan amount is approximately 1.13 million rubles .
This is an important point for any buyer: when comparing bank offers, you need to consider what additional products and services are included in the loan. If the cost of insurance is paid with borrowed money, interest is accrued not only on the car.

Five years: payment of about 27 thousand rubles
At first glance, a five-year loan looks quite comfortable.
At a rate of 14.9% per annum, the payment is about 26,850 rubles per month.
Such an amount may seem acceptable against the backdrop of the cost of a new car. However, the convenience of a small monthly payment comes at the cost of the length of the contract.
Over five years, the interest alone will amount to approximately 481 thousand rubles.

That is, a car worth 1.35 million rubles turns into a much more expensive purchase. And this does not include fuel, maintenance, tires, compulsory motor insurance, and other owner expenses.
Therefore, it makes sense to evaluate a car loan not only based on the principle of “will I be able to pay 27 thousand rubles a month?”, but also based on the question of “how much money will I give the bank over five years?”
Seven years are cheaper each month – but more expensive in the end
The bank may offer to stretch out the payments up to seven years.
The monthly payment then decreases to approximately 21,745 rubles .
The difference compared to a five-year loan is about 5,000 rubles per month. For a buyer on a budget, this can be a significant argument.

But the final overpayment increases to more than 696 thousand rubles .
That is why a long-term car loan often creates the illusion of affordability. The car becomes cheaper for the family budget every month, but more expensive for the wallet throughout the entire term of the contract.
In the case of Niva, the difference is especially noticeable: in this scenario, the total costs of the car approach 2.1 million rubles .
CASCO can increase costs
When calculating the cost of Niva, one must not forget about insurance.
In the loan program under consideration, the first CASCO policy is included in the loan amount. But with a long-term loan, the insurance must be renewed.

This means that seven years of the loan is not just 84 monthly payments.
The family budget will have to take into account the annual costs of CASCO. In addition, refusal of the insurance provided by the contract may lead to a revision of the interest rate.
Therefore, before signing the contract, it is important to study not only the advertised rate, but also the entire list of lending terms.
There is also an option with an almost zero rate
For buyers with large savings, a fundamentally different approach is offered.
With a down payment of 50% of the car’s cost – 675,000 rubles – you can take advantage of a program with a symbolic rate of 0.01% per annum .
The term is only 12 months.
The remaining amount together with CASCO is about 725,000 rubles. The monthly payment amounts to approximately 60,417 rubles .
The amount appears significantly heavier than a five-year loan, but the interest overpayment is virtually non-existent.
In essence, the buyer exchanges the low cost of financing for a high monthly burden.
And here everyone should evaluate their own capabilities: a payment of 60 thousand rubles can turn out to be a much more serious burden than an overpayment of several hundred thousand rubles on a long-term loan.
Three Nivas for the price of one? The math isn’t quite that way
The phrase that in seven years the buyer “pays off one and a half Nivas” sounds impressive, but it should be taken as a comparison, not a literal calculation.
The basic cost of the car does not disappear: the buyer pays for the car itself in any case. Additional expenses are formed from interest on the loan and insurance.
Therefore, it is more correct to talk about the full cost of financing , and not about the fact that the bank literally sells the owner a second car.
This important distinction helps to soberly evaluate car loans and not confuse the price of the car with the price of borrowed money.
Which option requires the least expenses
If we consider only the given mathematics, the loan term gives very different results.
At five years, the monthly burden is about 26,850 rubles, and the interest is about 481 thousand.
At seven years, the payment decreases to 21,745 rubles, but the interest exceeds 696 thousand rubles.
An annual program with a 50% down payment requires a payment of about 60,417 rubles, but in practice does not give an interest overpayment.
Moreover, the final decision depends not only on arithmetic. The buyer needs to leave a reserve for car maintenance and unforeseen repairs, and not direct all savings to the down payment.
For Niva this is especially important: the car is bought not only for the city, but also for use on bad roads, where the load on the suspension, transmission and body can be higher than usual.
What to check before applying for a loan
Before signing the contract for the Lada Niva Legend, you should request from the dealer and the bank a full calculation:
- down payment;
- exact loan amount;
- CASCO cost;
- monthly payment;
- total amount of payments;
- full cost of the loan;
- insurance extension conditions;
- consequences of refusing CASCO;
- possibility of early repayment;
- conditions for changing the interest rate.
The last point is especially important for a long-term contract. The low rate advertised in the promotional offer isn’t always maintained if the program terms are violated.
Bottom Line
A Lada Niva Legend Urban for 1.35 million rubles looks completely different if you look at the full purchase price rather than the showroom price.
A five-year loan makes the purchase significantly more expensive due to interest. A seven-year contract further increases the final cost, although it reduces the monthly payment. A one-year installment plan almost eliminates interest overpayments, but requires a 675 thousand ruble down payment and more than 60 thousand rubles monthly.
The main conclusion here applies not only to the Niva: when buying a car on credit, you need to compare not the monthly payment, but the entire amount that you will have to pay down to the last ruble .